

(Image: Micron G8 QLC NAND, courtesy of Micron Technology, Inc.)
It would be an understatement to say that $MU’s earnings today are high stakes.
If the market receives it positively, it could help push both the S&P 500 and the Nasdaq to new all-time highs.
If the reaction is negative, it could trigger a real meltdown — not in isolation, but against a backdrop of the highest 10-year Treasury yields since before the Global Financial Crisis.
Micron was the very first stock I ever published as my #1 QuantRanks pick. I said I was buying it the day before, and bought it at the open on Monday, Aug 10, at $863.67 — and again on Sept 8, at $1,036.40.
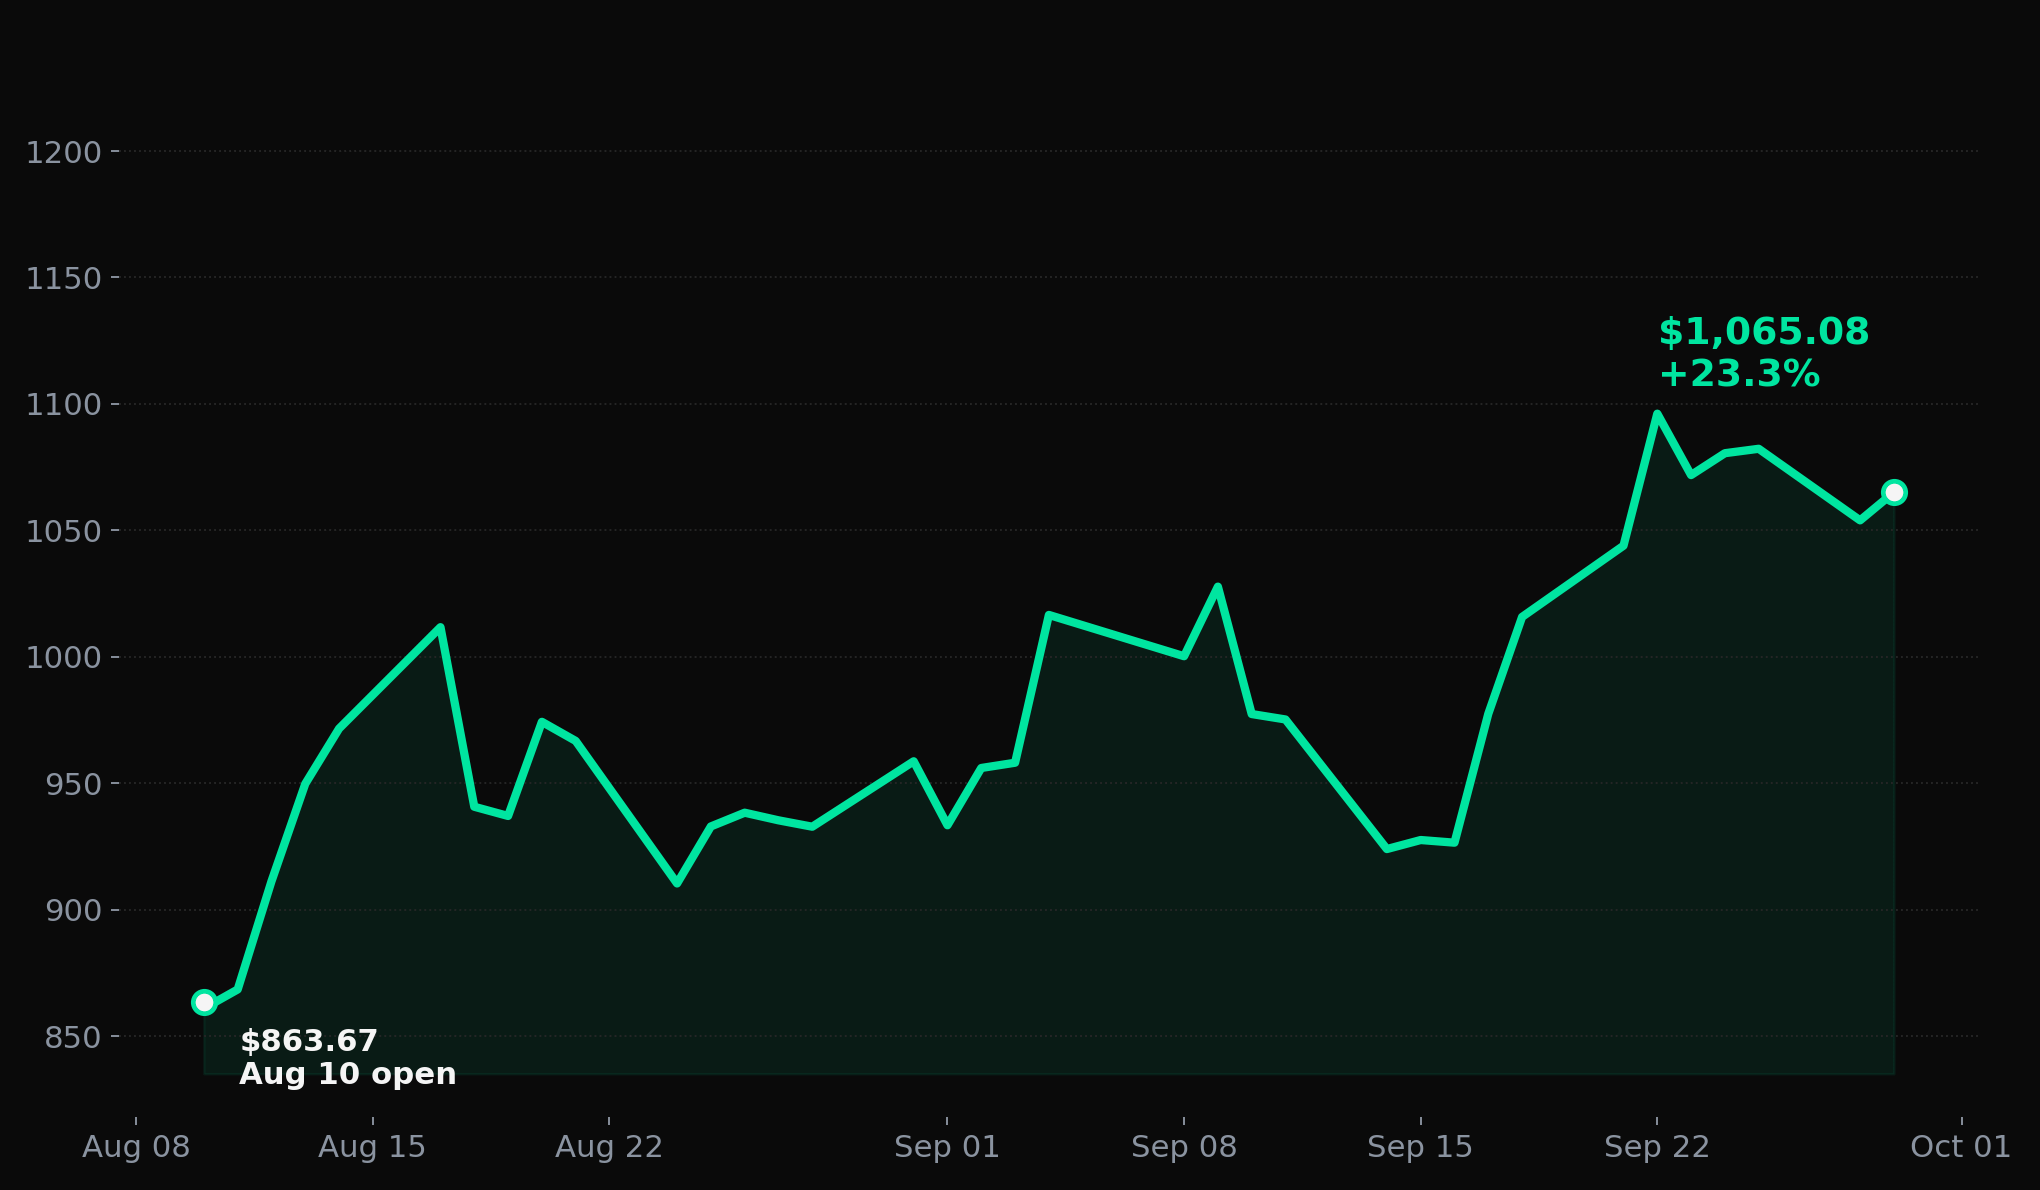
As of Tuesday’s close, I’m up 23.3% on my Aug 10 buy.
Micron reports fiscal Q4 earnings today, after the close. This is the AI trade’s other bellwether — not the GPU maker everyone already has an opinion on, but the company that makes the memory those GPUs can’t function without. Every AI server, every large model, every “longer context window” the industry keeps promising runs through a memory chip first.
MU: Positives vs. negatives heading into earnings
There’s been a real arm-wrestling match playing out in markets lately — bulls against bears, equities against rising oil prices and climbing yields. Here’s what I’m weighing, briefly, on both sides:
Positives:
Demand is outrunning supply industry-wide — Micron’s own filings say AI-driven memory demand is growing faster than the whole industry can supply it, not just Micron’s own capacity
Meta’s Muse is a fresh, specific catalyst — one of the stock’s most bullish analysts points to it as new evidence AI demand is broadening, not slowing
Micron’s Cloud Memory and Core Data Center business-unit revenues surged 307% and 653% year over year, respectively
The product roadmap extends past this quarter — a new 512GB DDR5 RDIMM for AI data centers, announced this month, won’t hit volume production until 2H 2027
Wall Street consensus is a Moderate-to-Strong Buy across 45 analysts, with an average target well above today’s price
Negatives:
Michael Burry has publicly increased his short position, citing stretched memory valuations
A potential labor strike looms at Micron’s Taiwan plant
Samsung just announced a major HBM4 capacity expansion — direct competition in Micron’s strongest segment
Short interest has been rising for months
The stock has already shown it can drop 5%+ in a single session on nothing more than sentiment, with zero change to the underlying business
None of that — bull or bear — is a call on what Micron actually reports today, or how the stock reacts. QuantRanks isn’t scoring analyst price targets, product launches, short interest, or competitive threats directly. It’s scoring the stock the same quant way it scores every other name in the universe.
With everything said, what’s its current rank and is it still a buy? Both answers right below
The stocks I’ve bought — and how they’ve done
Before I answer both questions on Micron, here’s the performance of every single stock I published and bought since Aug 10 based on the same QuantRanks ranking system — no cherry-picking, marked to Tuesday’s close:
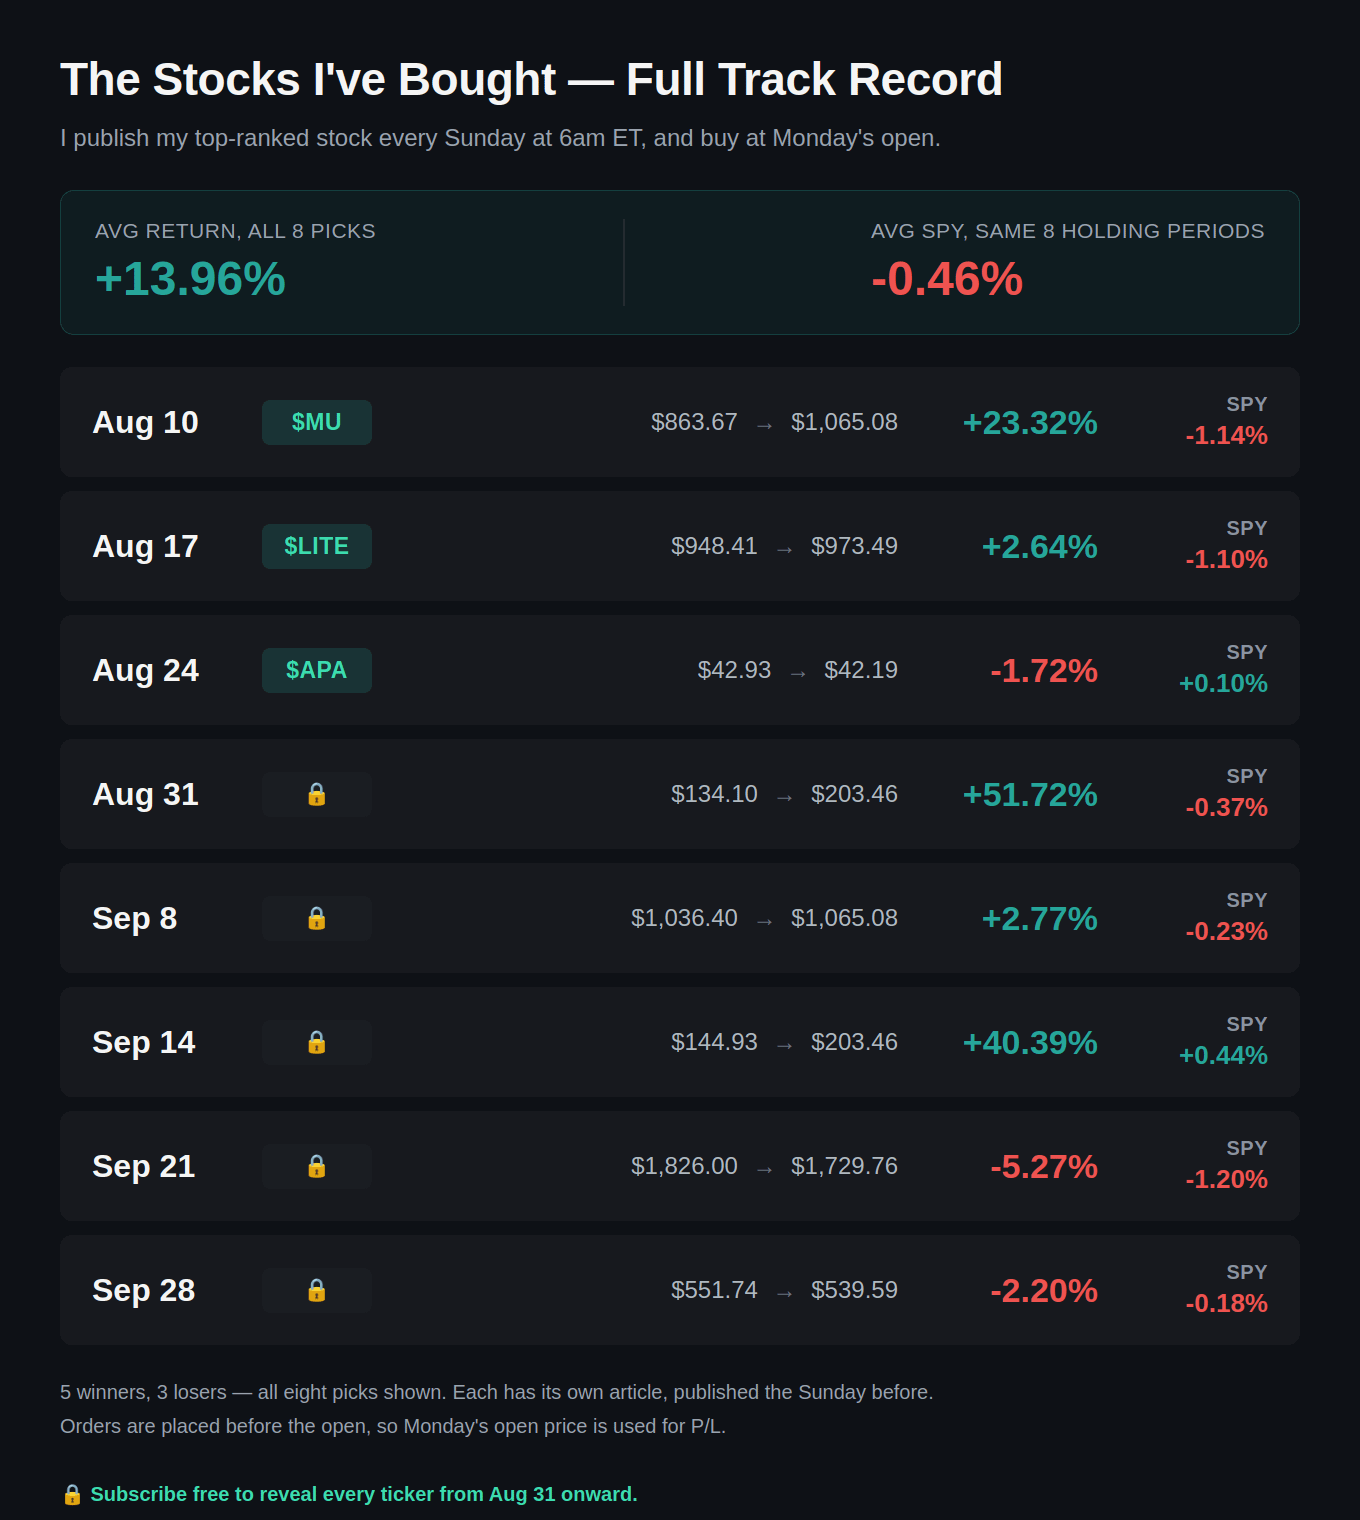
Five winners, three losers, an average return across all eight that’s meaningfully ahead of just holding the index over the same stretch. Five of those tickers are hidden above.
Subscribe for free to see MU’s current QuantRank, the verdict, and every ticker in the track record above.
I bought DRAM which has a decent stake in MU. Personally bullish.