

Update: This is my founding post, first published July 21, 2026 with a backtest through July 2026. I’ve extended the Portfolio Visualizer backtest through the end of August 2026 and refreshed every chart and number below. Nothing about the system changed — only the data got longer.
I am an engineer. Not a banker, not a finance-school graduate — an engineer who spent more than twenty years obsessed with a single question about the stock market.
Engineers are trained to find the signal inside the noise. Hand us a chaotic system and we will take it apart, measure it, and ask the same stubborn question for years: what actually drives this?
For me, that system was the market. And the question that wouldn’t let go was simple: is there a reliable way to know when to be invested and when to step aside?
Not stock-picking. Not predicting the future. Just that one binary decision, made well, repeatedly, for decades. Because if you get it right, you avoid the catastrophic losses that quietly destroy most people’s wealth — the 50% drawdowns that take years to climb out of.
More than twenty years of quantitative research and 26+ years of backtesting later, I had my answer.
And I’ve come to believe it may be the simplest effective investment system in the world.
Never miss a Market Signal or Stock Recommendation. Subscribe Free For Limited Time
This isn’t just a backtest
The signal is live and public. I’ve posted every SPY signal as it happens since July 26, 2026, and since August 10 I’ve also published a weekly stock pick from QuantRanks, my monthly stock-scoring model. After each month closes, I post my full portfolio and its performance, wins and losses both.
My first monthly report, for August 2026, showed my full portfolio up 8.14%, against 2.68% for SPY. One month proves nothing on its own, but it’s on the record, and every month after it will be too. Read the full August portfolio update →
The backtest below shows how the system behaved across 26+ years. The live record shows what it’s doing now.
Let me show you what it did. The figures below were calculated by Portfolio Visualizer, with every SELL period modeled as held in cash.
What changed with the August update
Short version: the extra month strengthened every number, and the risk profile didn’t move.
Ending balance: $1,752,776 → $1,808,805
CAGR: 21.45% → 21.52%
Sharpe ratio: 1.77 → 1.78
Sortino ratio: 5.65 → 5.67
Maximum drawdown: unchanged at −8.48%
Worst calendar year: unchanged at +6.22%
$10,000, two paths, 26+ years
Here is the same $10,000 invested in the S&P 500 from January 2000 to August 2026 — more than a quarter century. One line simply buys and holds SPY. The other follows my market timing signal: in the market when it says BUY, in cash when it says SELL.
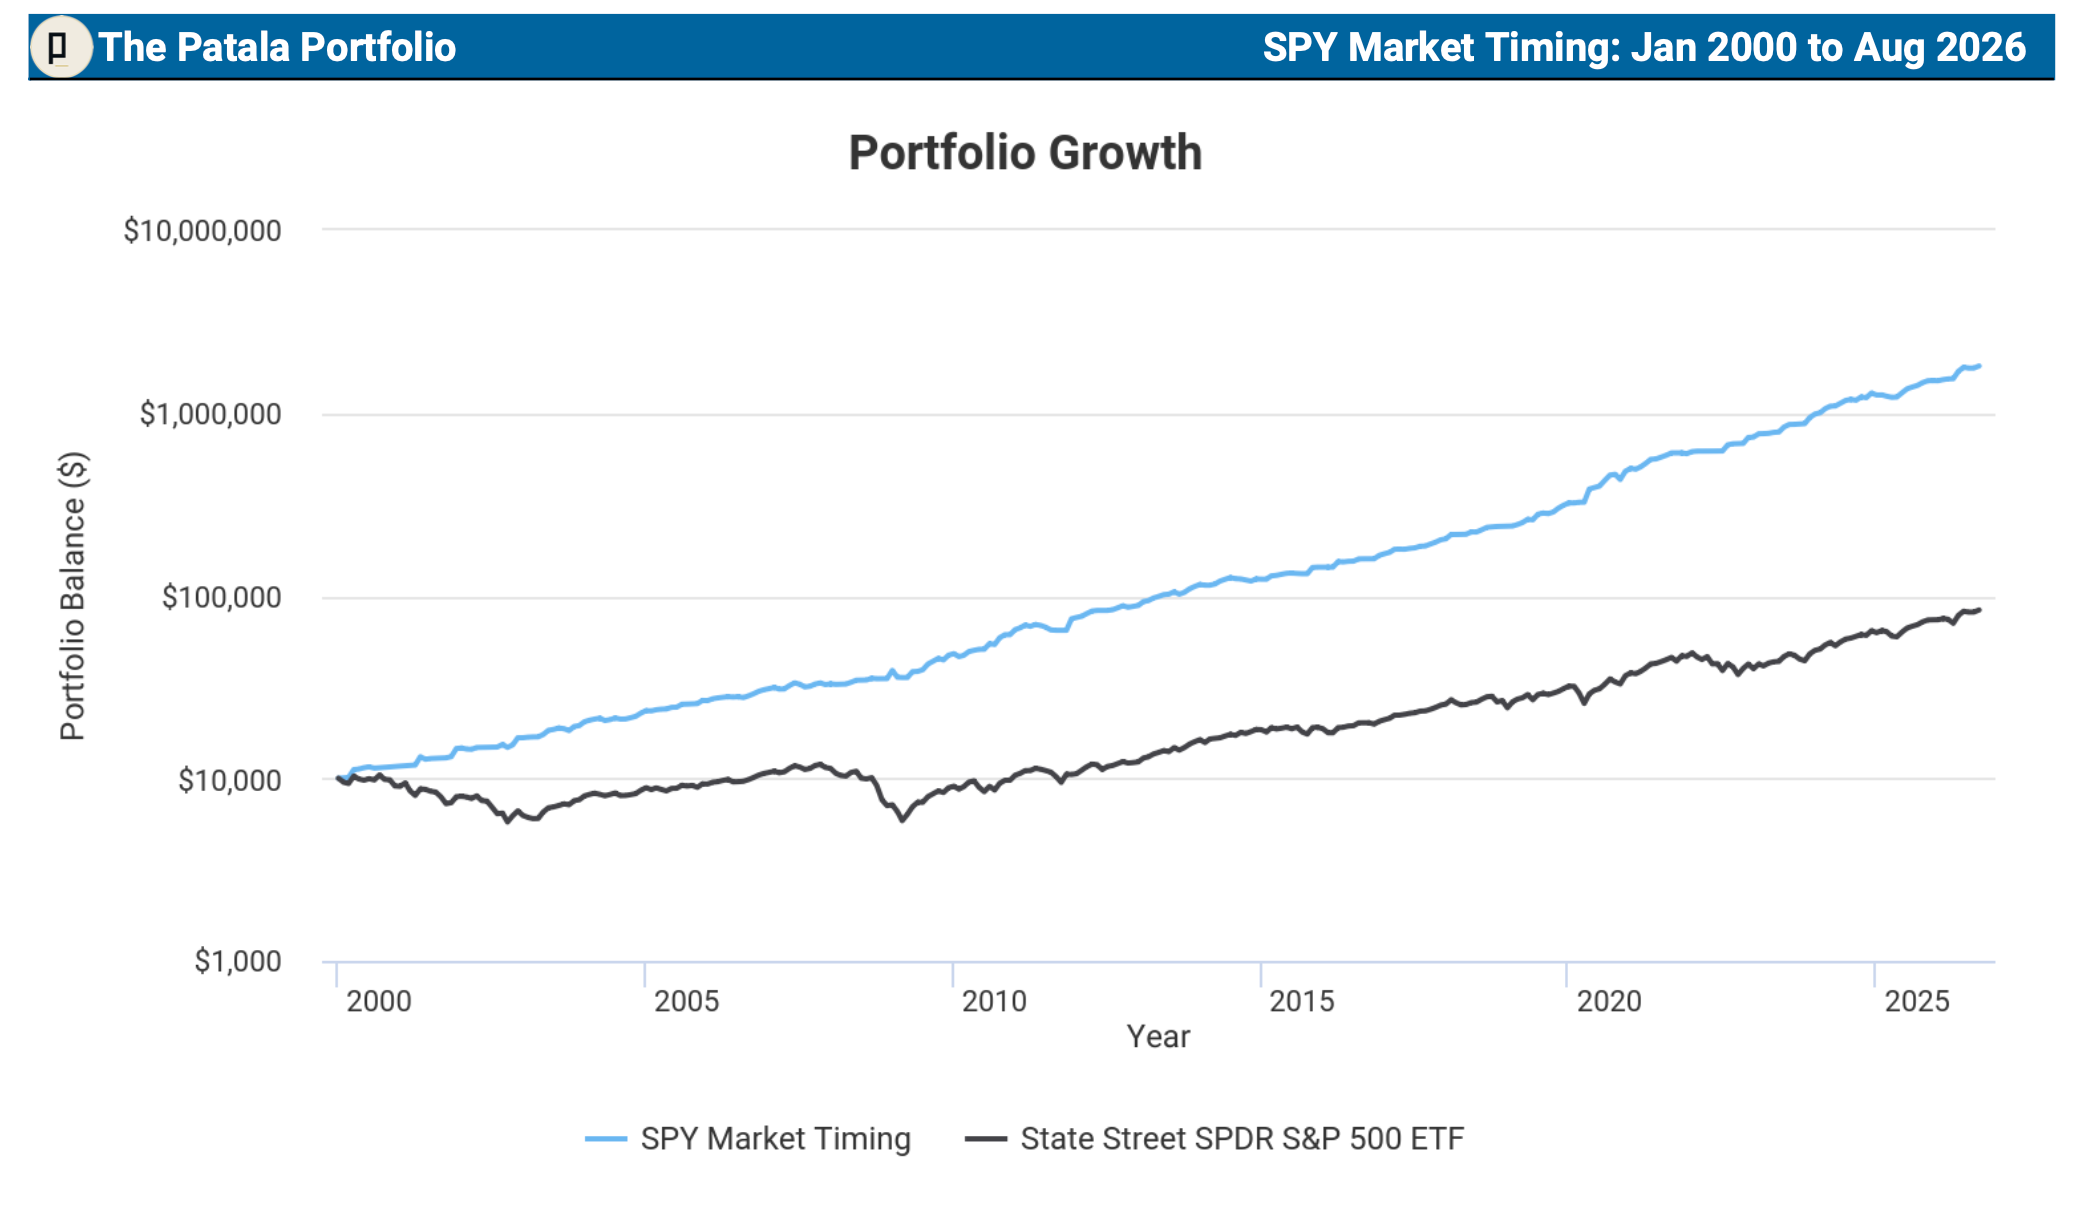
Same index. Same starting amount. The only difference is knowing when to step aside. Over these 26+ years the timing system turned $10,000 into $1,808,805. Buy and hold turned it into $83,409. That is more than 21 times the ending wealth — from the same index, driven entirely by one decision made consistently across more than two decades.
Even after adjusting for inflation, the system ends at $908,776 in today’s dollars. Buy and hold ends at $41,906.
But the returns aren’t even the best part
Here’s what took me years to fully appreciate: the power of this system isn’t in the gains. It’s in the losses it avoids.
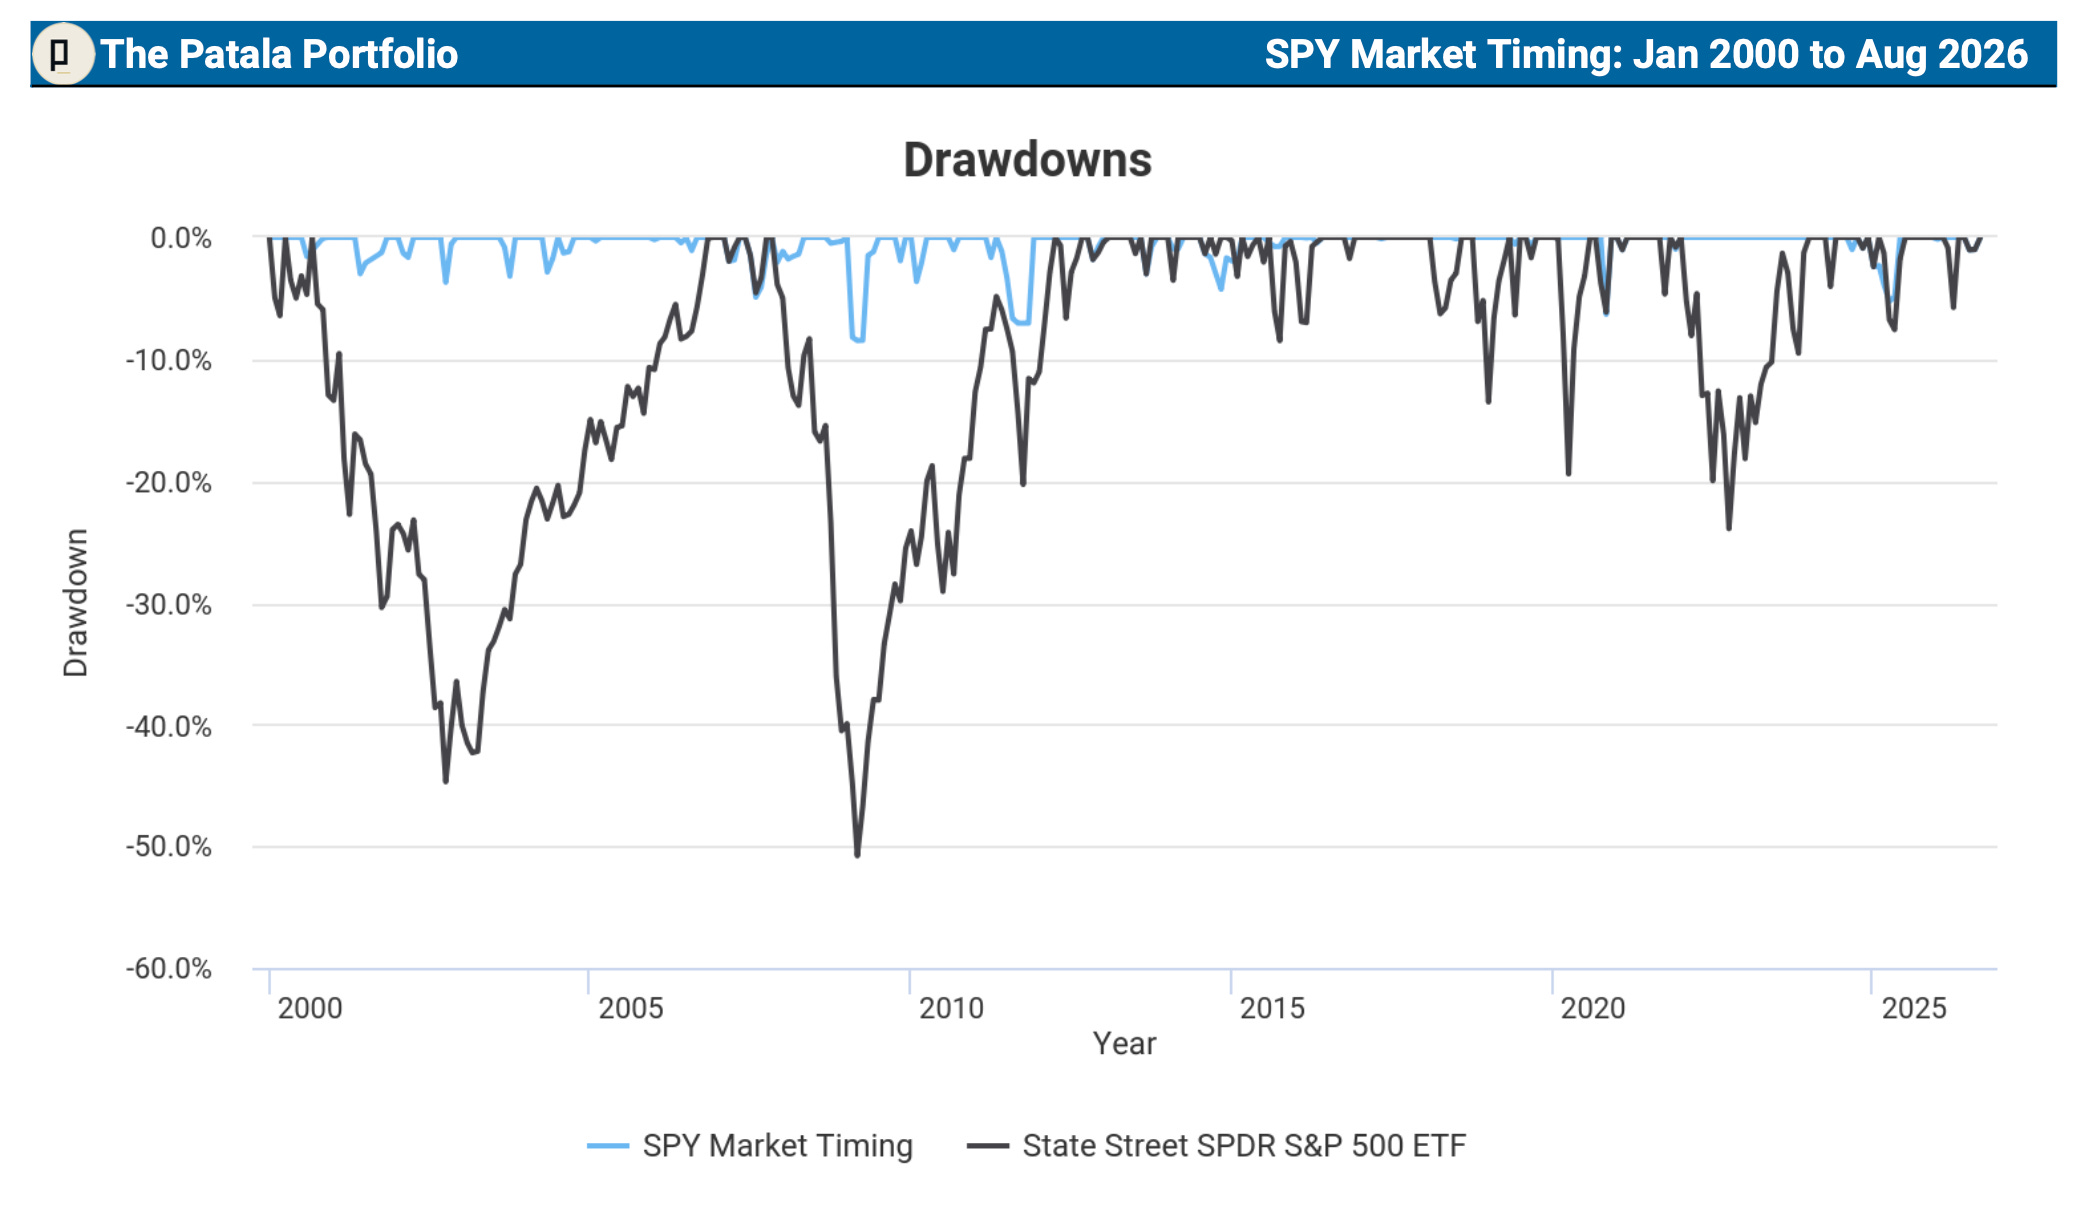
Look at that chart. Across 26+ years — when the dot-com crash took the S&P 500 down 44%, and the 2008 crisis took it down 50% — the timing system was sitting in cash. Its worst drawdown over the entire period was just 8.5%.
The stress-period numbers from the report tell the whole story:
Dot-com crash (2000–2002): system −3.7% vs buy & hold −44.7%
Subprime crisis (2007–2009): system −8.5% vs buy & hold −50.8%
COVID-19 crash (2020): system −0.04% vs buy & hold −19.4%
The system didn’t win by reaching higher. It won by falling less — and by never having a deep hole to climb out of.
Every risk measure, side by side — 26+ years
Let me give you the full dashboard rather than a cherry-picked stat. This comes directly from the Portfolio Visualizer report, covering January 2000 through August 2026:
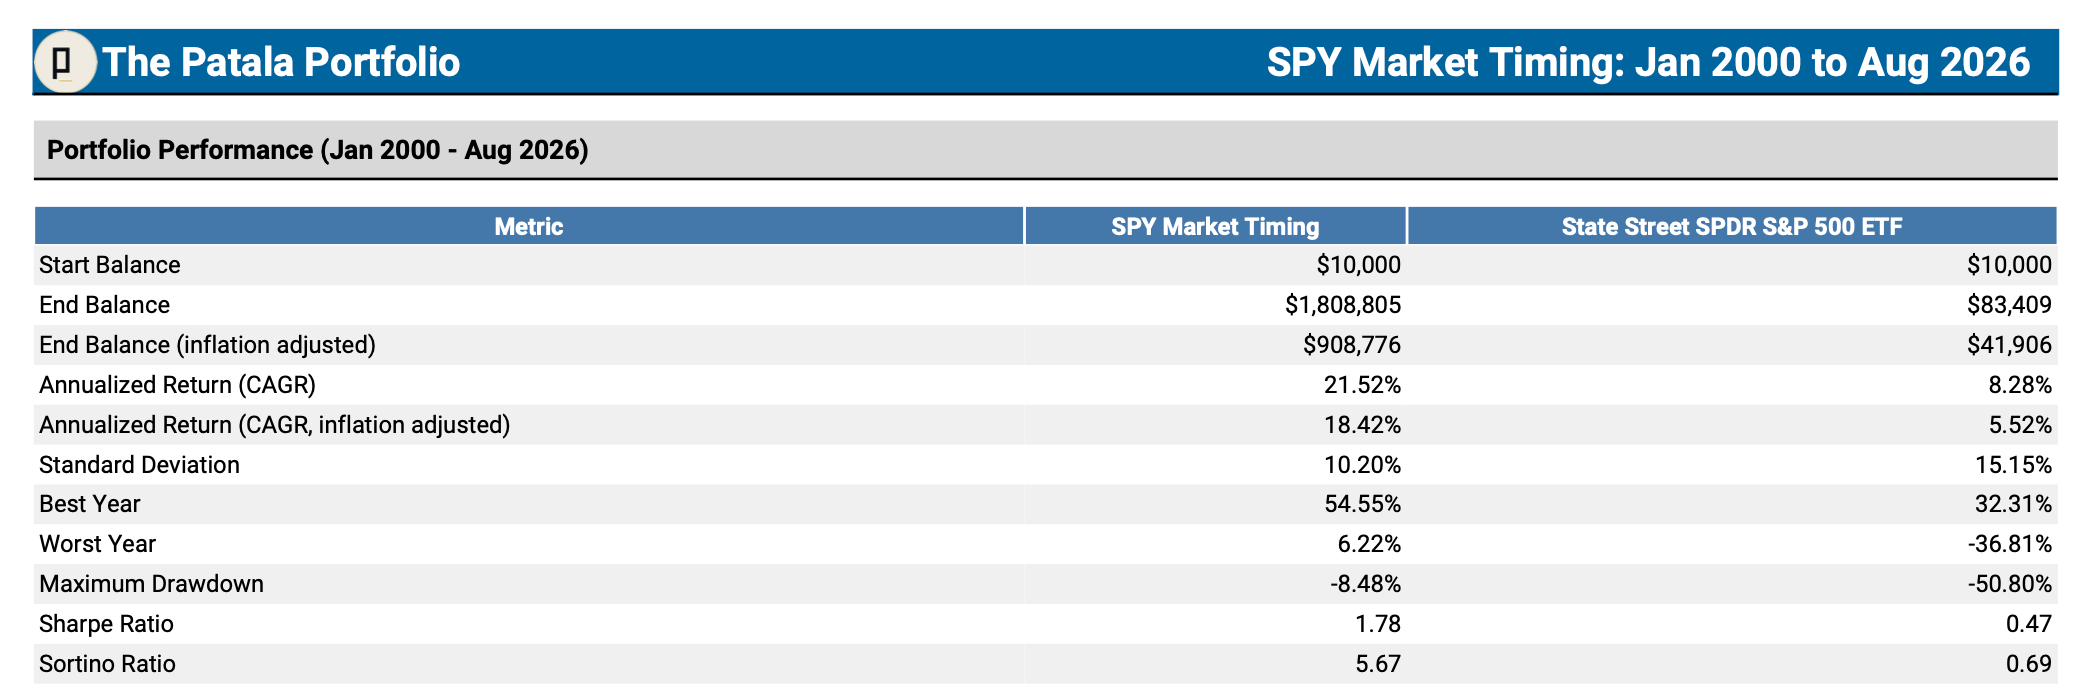
Read the worst-year line twice. Across 26+ years, the system’s worst calendar year was positive — up 6.22%. It never lost money in a full year, through the dot-com crash, 2008, COVID, and 2022. Buy and hold had a −36.81% year.
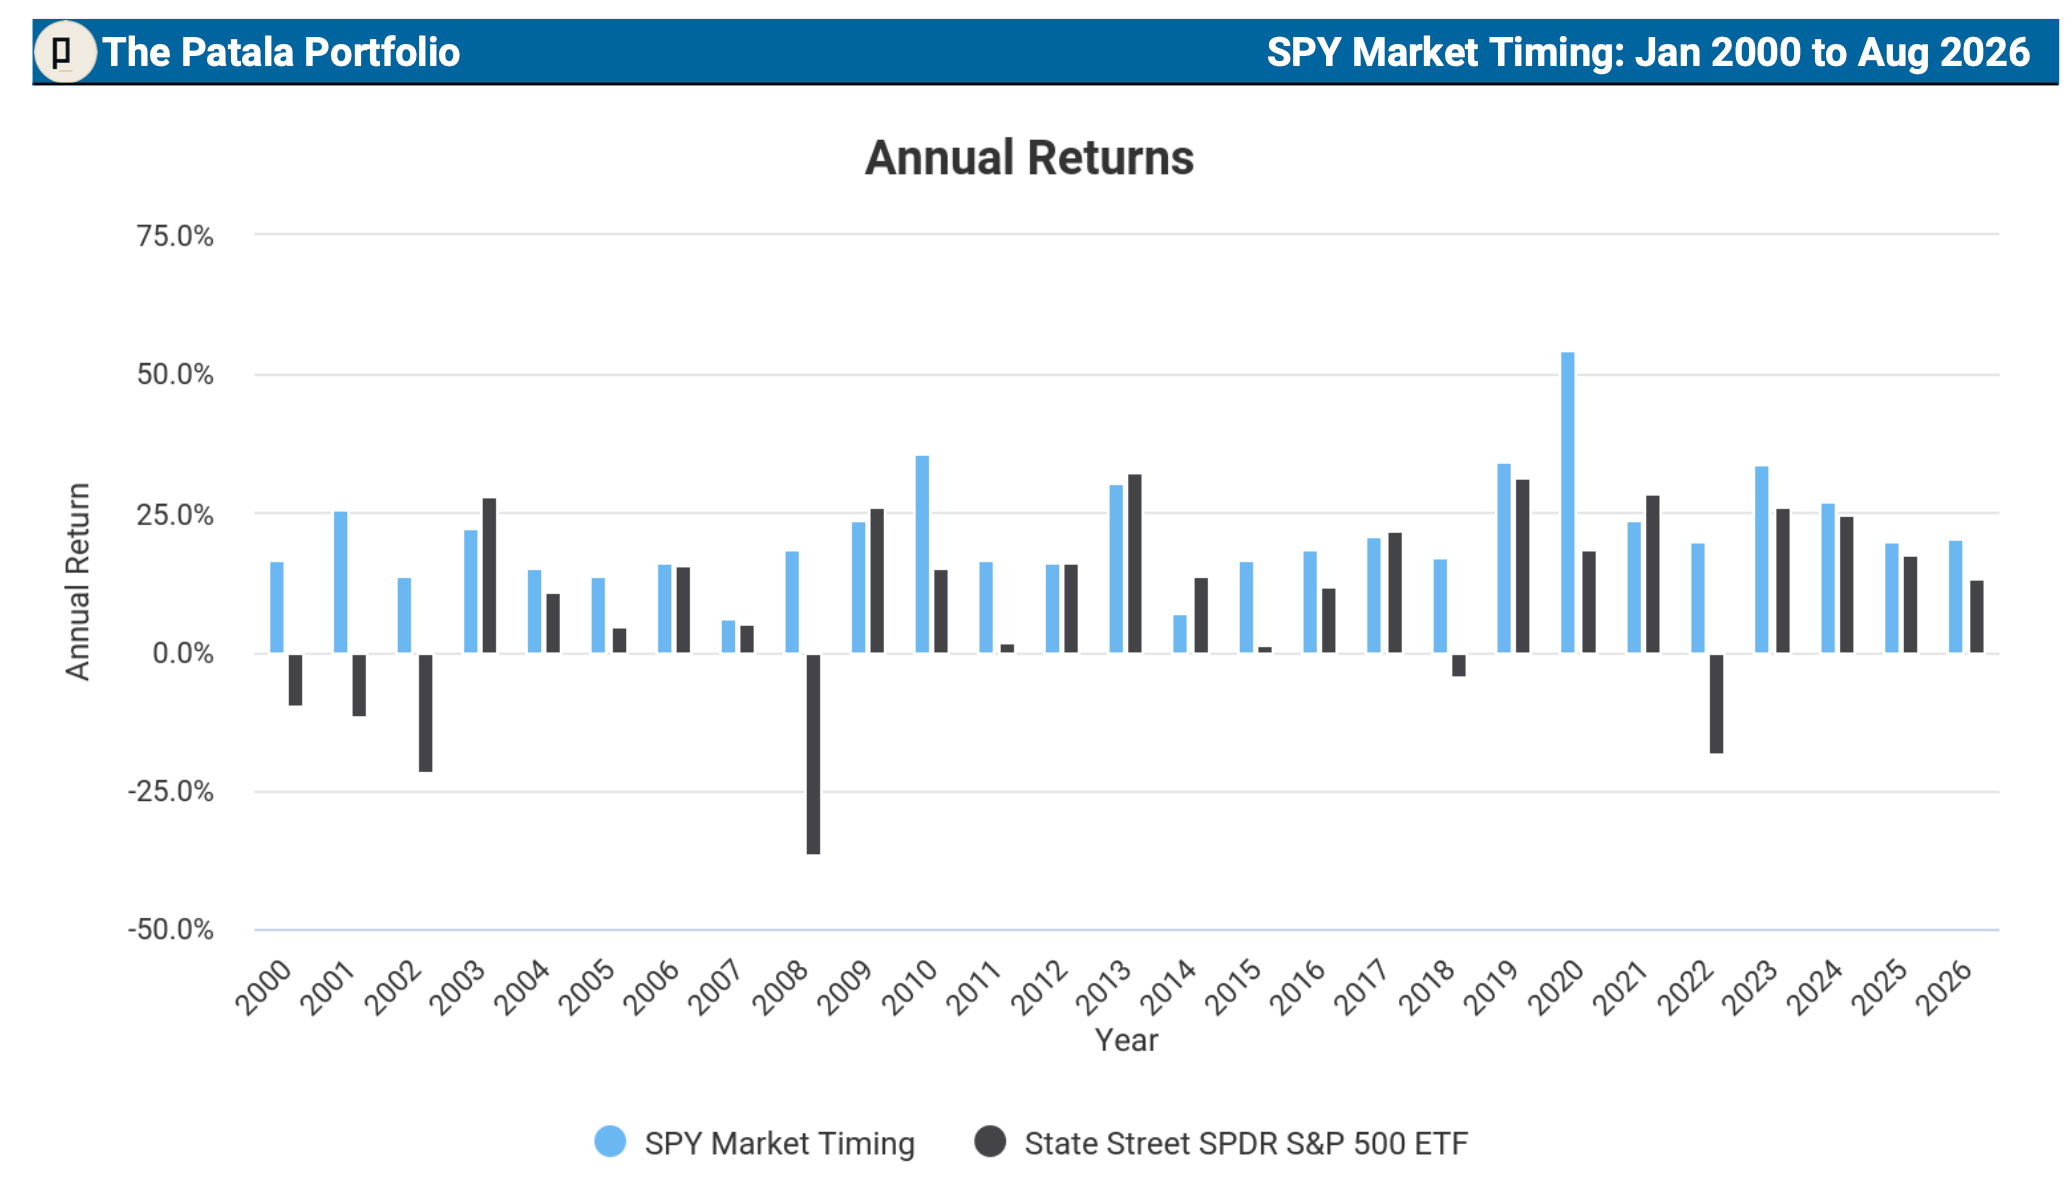
Every blue bar sits above zero. Every one of the black bars that drops below it — 2000, 2001, 2002, 2008, 2018, 2022 — is a year the system stayed positive.
And notice the risk-adjusted ratios. A Sharpe of 1.78 versus 0.47. A Sortino of 5.67 versus 0.69. Over more than two decades the system produced far more return for every unit of risk — with lower volatility (10.20% vs 15.15%) and higher returns (21.52% vs 8.28% a year) at the same time. That combination is supposed to be difficult. Here it comes from a single discipline, applied consistently for 26+ years.
How it works — two layers
I built it the way an engineer builds a control system: one layer to set direction, a second, faster layer to react to the present.
Layer 1 — The macro model. On the first trading day of each month, it produces a single call: BUY or SELL. This is the strategic backbone, reading the broad market environment.
Layer 2 — The daily zones. Every day, the model divides the S&P 500 into 158 distinct zones. Only 11 of those zones trigger a SELL. Everything else means stay invested. Layer 2 catches danger that arrives mid-month.
That second number is the heart of the design. Out of 158 zones, only 11 say “get out.” The model is built to stay invested — it ignores routine dips and sideways chop, and only steps aside when price enters genuine danger. The bar to leave the market is deliberately high, and 26+ years of backtesting is what calibrated exactly where those danger zones sit.
Subscribe free for a limited time
How you actually use it
At the end of each trading day, the system produces the signal for the next trading day. Two states, two actions:
BUY → be 100% invested in your chosen asset.
SELL → be 100% in cash.
That’s the entire operating manual. You check the signal after the close; if it changed, you place one trade the next day. Most days, nothing changes at all.
How I actually apply it
The signal is the foundation. Because it reads the S&P 500 — the core of the US stock market — I use it to govern everything I hold in US stocks. How much you build on top of it is up to you.
Level 1: My personal 401(k) version (5 to 8 hours a year). This is the simplest way to run the system, and it’s how I run my own 401(k). When the signal says BUY, I hold a broad US large cap index fund. When it says SELL, I move to the plan’s stable value fund. There are no taxes on the trades, no special account, and no stock picking.
Level 2 — Core-Plus. The same signal governs a core position in QQQ — or, for the aggressive, TQQQ — plus smaller sleeves of the top-ranked stocks from QuantRanks, my monthly stock-scoring model. It offers more return potential, with more risk and more work. Read the full Core-Plus strategy →
What’s next
The QQQ backtest — the Nasdaq 100, where buy & hold fell 83% in the dot-com crash, and where a $10,000 stake grew into millions — will be extended through the end of September and published in October.
If you want a patient, systematic, hype-free approach to the market, follow along.
The simplest market timing signal in the world. One signal. One trade when it flips. Backtested across 26+ years. Five to eight hours a year to run.
Subscribe free to follow The Patala Live Portfolio
Disclaimer: I am not a registered investment adviser, and nothing here is personalized investment advice, a recommendation, or an offer of advisory services. This publication is for informational and educational purposes only. Performance figures are generated by Portfolio Visualizer from historical data and a backtested application of the signal; backtested results are hypothetical, have inherent limitations, and do not guarantee future results. Consult a qualified financial adviser before investing. You are solely responsible for your own decisions.
Thank you for update..
Still looking for your feedback/response on my review of 2 of your articles and the discrepancies..I had posted this earlier..
“Hi .. could u kindly explain why your 10 SPY flips shown in article dated 9/19 is different from the one shown in the article dated August 1. The returns/some dates shown do not match. Creates the impression of the accuracy of the data . Thank you again”